DIEGO F PARRA · CREATOR OF THE MASTERESTAURANT® METHODOLOGY
Restaurant contribution margin calculator for every dish: formula and free sheetThe toolkit sheet to work out how much each menu item contributes toward fixed costs
The unit contribution margin is what each dish sold leaves after its variable cost: selling price before tax minus unit variable cost. This restaurant contribution margin calculator is the MASTERESTAURANT printable sheet to work it out dish by dish, free to download, in Spanish.
Why calculate the contribution margin of each dish
Calculating the contribution margin of each dish is the most direct way to know how much every menu item brings to the business. It shows which dishes create the most value and which need cost or price adjustments to line up with the restaurant's financial goals, and it keeps decisions from resting on assumptions or gut feeling.
With that number you design prices and promotions, adjust the food and beverage lineup and put marketing dollars behind the dishes that contribute most. The sheet on this page is part of the MASTERESTAURANT digital toolkit, designed by Diego F. Parra to download free, print and use with the standard recipe of each dish.
What is the unit contribution margin of a dish?
The unit contribution margin is the money each dish sold brings in after covering its variable cost, mostly ingredients. That money pays the restaurant's fixed costs and, once they are covered, becomes profit.
You will also see it called unit margin, contribution per unit or simply the contribution margin of a dish, and it is expressed two ways: in dollars, how much each sale contributes, and as a percentage, what share of the price is margin. A dish's contribution margin is not its profit: you still have to pay rent, fixed payroll, utilities and marketing, which do not change whether you sell one more plate or one less. That is why it is called a contribution: each sale contributes to covering those fixed costs. Working it out dish by dish shows which menu items carry the business and which need a price, portion or ingredient adjustment to line up with the restaurant's financial goals.
What is the unit contribution margin formula?
Unit contribution margin = selling price before tax − unit variable cost. As a percentage: CM % = unit CM ÷ selling price before tax × 100. The price goes in before tax because sales tax is not restaurant revenue.
Unit variable cost is what it takes to produce and sell one unit of the dish: the portion cost from its standard recipe plus any other cost that rises with each sale, such as packaging or a delivery app commission. For example, if a dish sells for $20.00 before tax and its variable cost is $6.00, the unit contribution margin is $14.00 and the CM % is 70%. When ingredients are the only variable cost, the CM % is the complement of the ingredient cost percentage: 100% minus that percentage. That is how the toolkit sheet works it out. If your operation pays direct labor per dish produced, add it to the variable cost too.
How do you fill in the restaurant contribution margin calculator sheet?
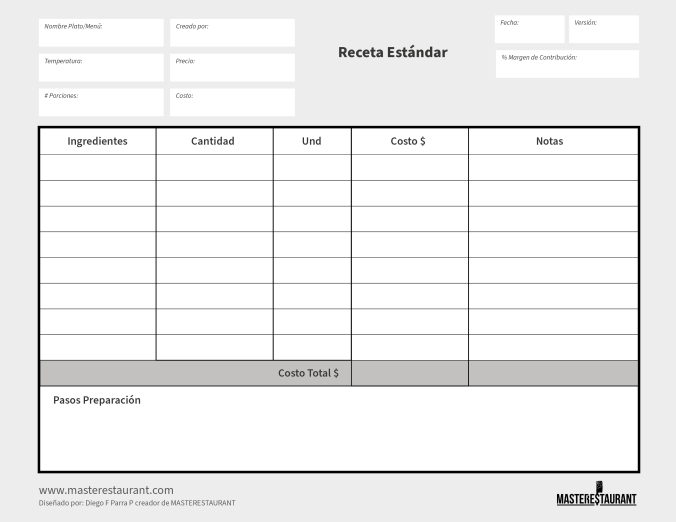
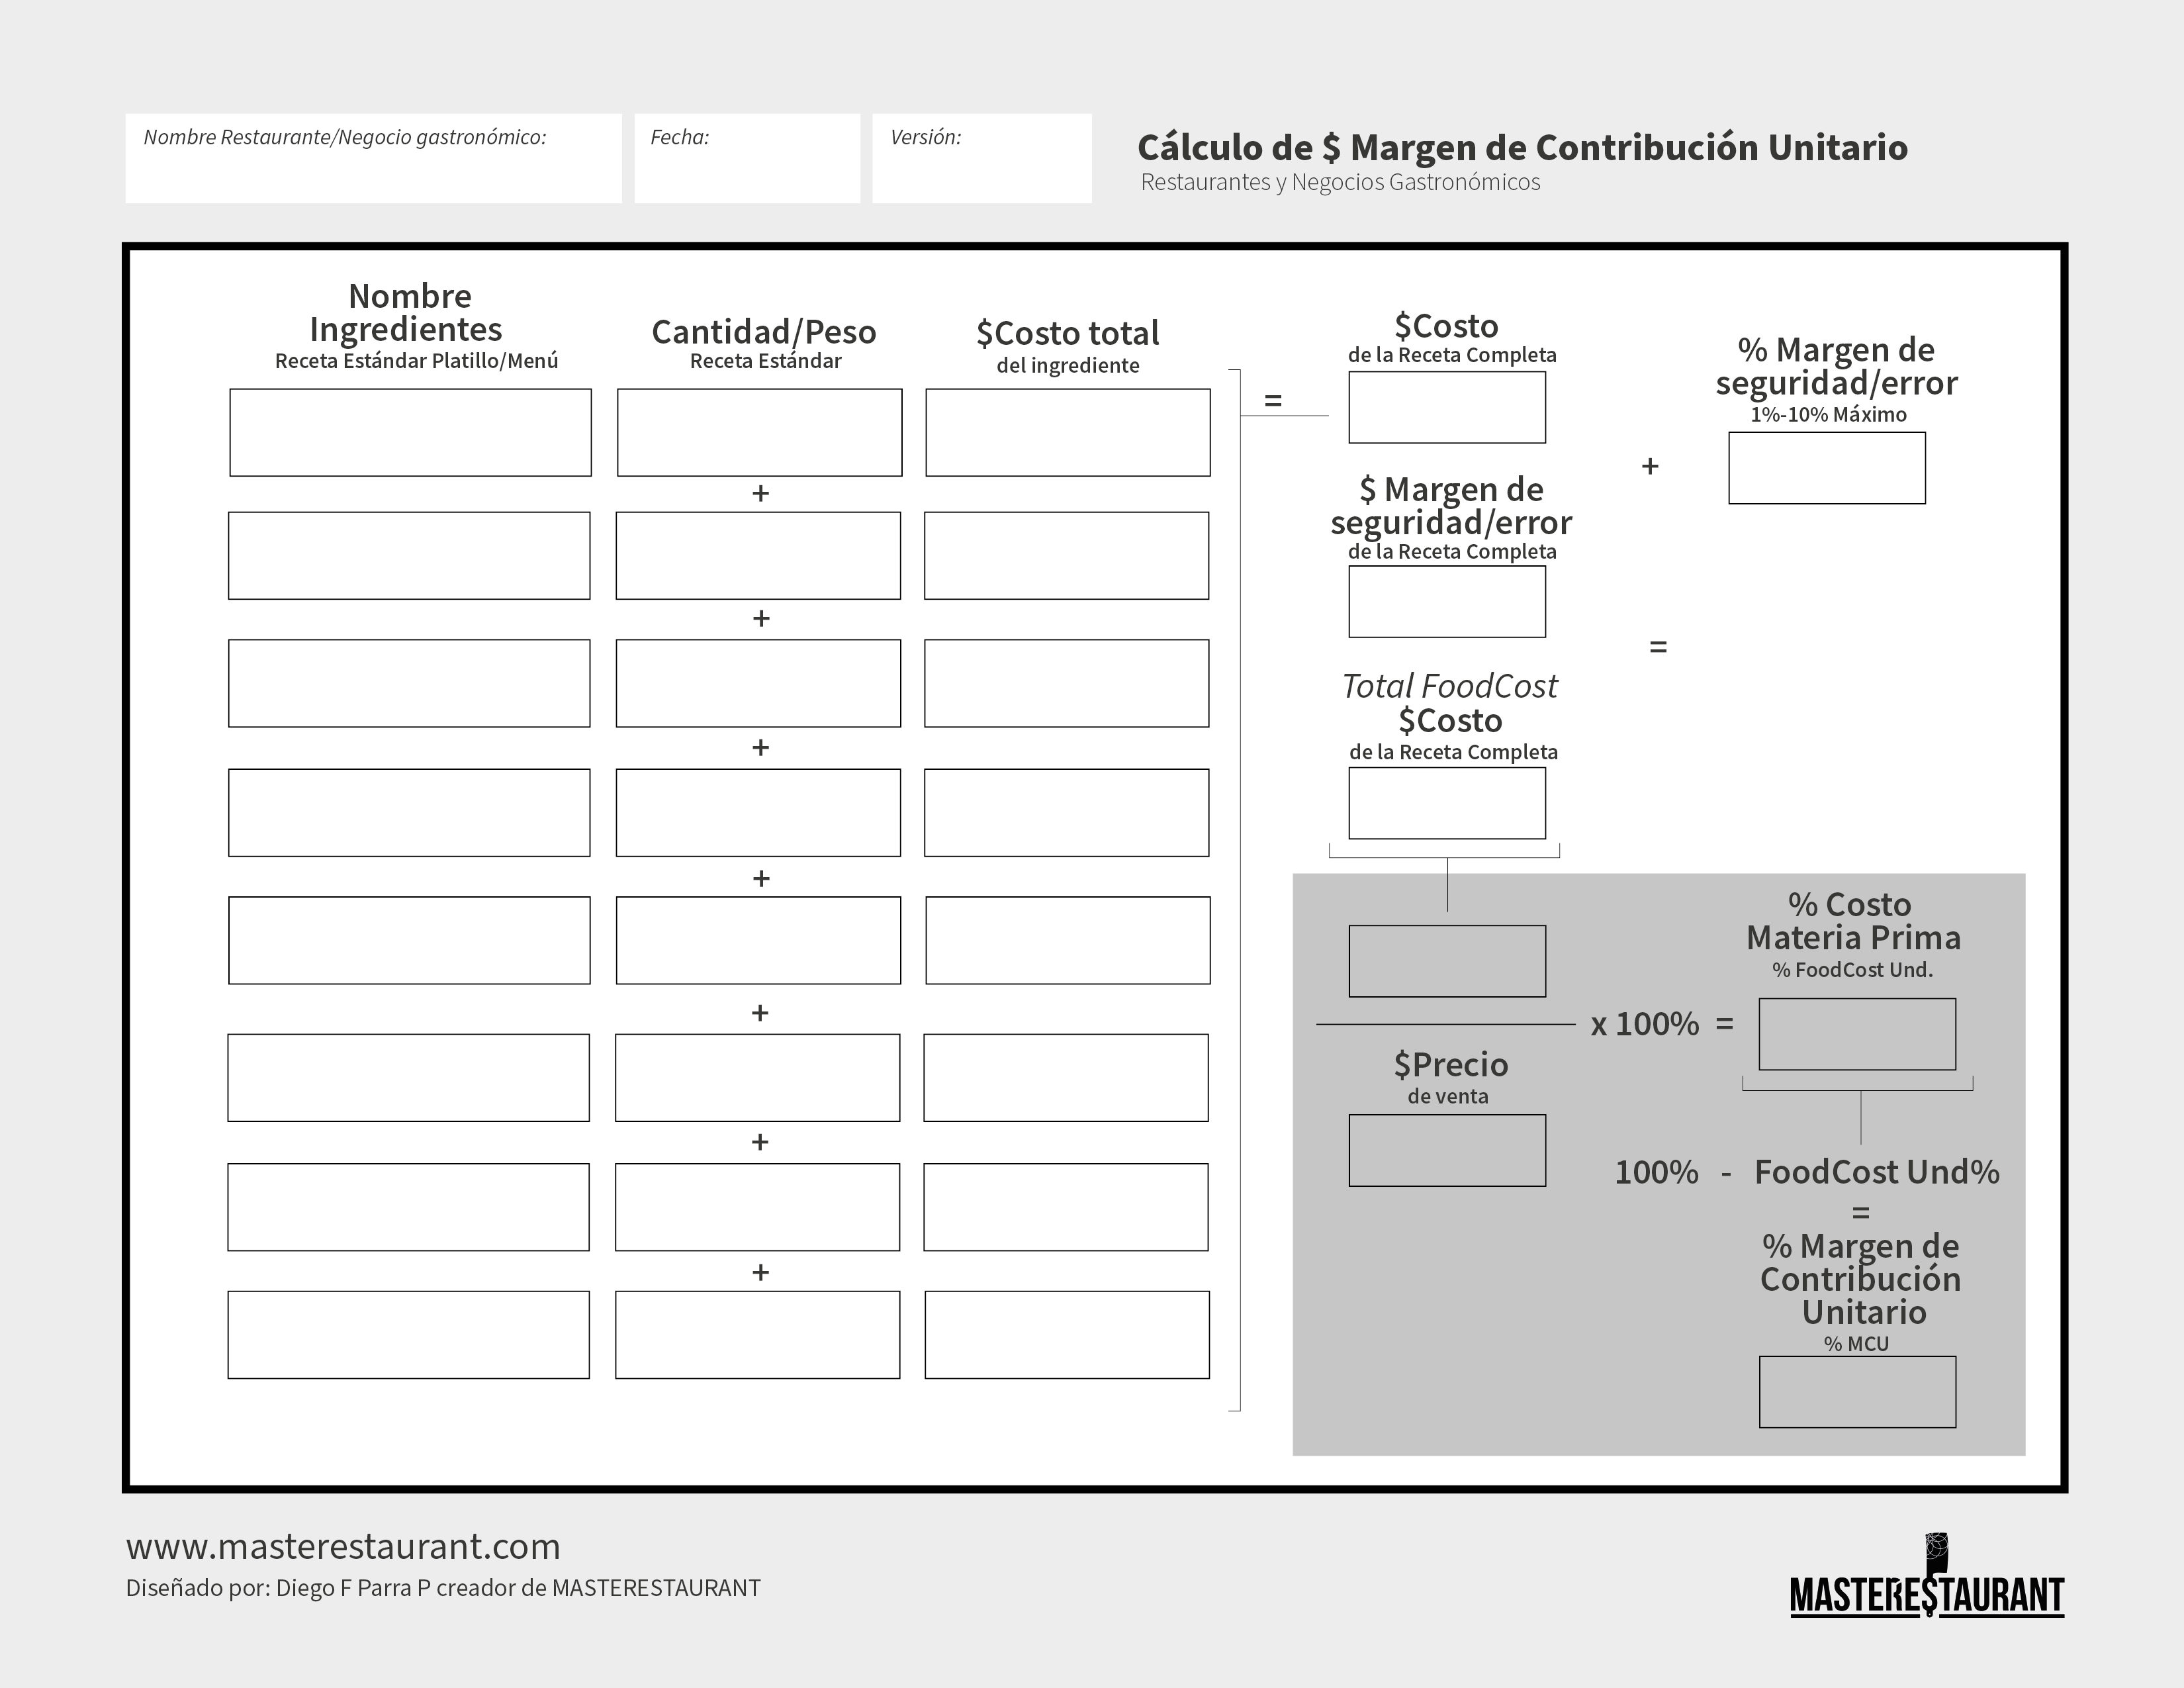
Copy the dish's ingredients from its standard recipe with quantity and cost, add them up, add a safety margin, divide that total cost by the selling price and subtract the result from 100%.
The top of the sheet holds the restaurant name, the date and the version. On the left goes each ingredient from the standard recipe with its quantity or weight and its total cost; the sum is the cost of the full recipe. To that cost you add a safety or error margin —the sheet sets it from 1% up to a maximum of 10%— to cover small swings in portion size and purchase price, and the result is the total ingredient cost of the dish. That cost divided by the selling price before tax and multiplied by 100 gives the ingredient cost percentage. Finally, 100% minus that percentage is the unit contribution margin percentage. The dollar value is the price minus the total cost.
How do you read menu item profitability dish by dish?
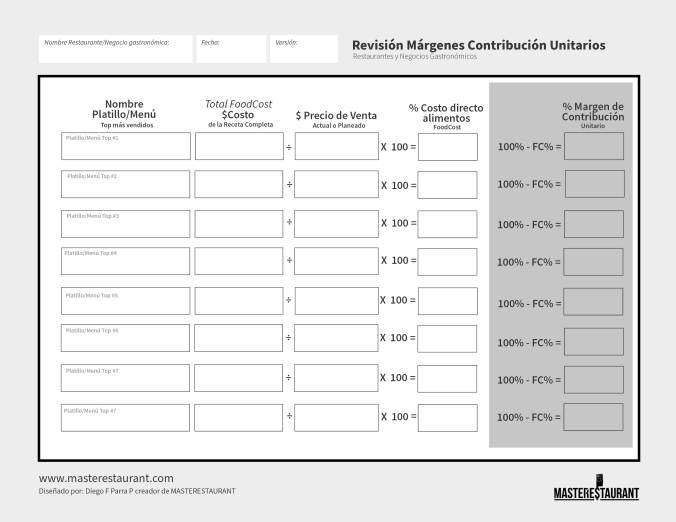
Look at both measures together: CM in dollars tells you how much each sale contributes, and CM % tells you what share of the price is margin. A dish can have a high percentage and earn little, or the reverse.
In the sample table on this page, the lemonade has the highest percentage and earns the least per unit, while the salmon has the lowest percentage and earns the most. If you only look at the percentage, you would push the lemonade; if you only look at dollars, the salmon. The decision comes from weighing each dish's unit margin against how many units it sells: one that earns a lot but rarely sells counts for less than one that earns a bit less and goes out to every table. With that reading you decide what to feature on the menu and in promotions, which dish needs a price, portion or ingredient change and which one no longer belongs. To see the menu's margin based on what actually sells, use the weighted margin sheet.
What counts as a good contribution margin for a restaurant?
There is no single number: it depends on the concept, the average check and fixed costs. A margin is good when the margin from a month's dish sales covers fixed costs and still leaves a profit.
That is why the unit contribution margin is read together with the break-even point: how many sales the restaurant needs for the accumulated margin to pay rent, payroll and the other fixed expenses. As a cost reference, based on Diego F. Parra's experience with more than 8,400 restaurants, the most common food cost range is between 22% and 38% of the selling price before tax; when ingredients are the only variable cost, the margin percentage is what is left of the price after that cost. More useful than any average is the trend on your own menu: if a dish's margin drops month after month, something changed in the purchase price, the portion or the recipe.
Is contribution margin the same as restaurant profit margin?
No. Contribution margin is calculated before fixed costs; restaurant profit margin is the share of sales left after paying all of them. That is why a dish can have a high contribution margin while the restaurant still loses money.
The chain works like this: price minus variable cost gives each dish's contribution margin; the sum of the margins of everything sold in the month gives total contribution; and total contribution minus fixed costs gives operating profit. If total contribution does not cover fixed costs, the restaurant is below break-even even though every dish “earns” a margin. That is why a restaurant's net profit is much smaller than the contribution margin of its dishes: it is measured at the end of the chain, not dish by dish. To see the margin of the whole menu, the methodology adds the weighted margin, which combines each dish's margin with its share of sales.
How does the contribution margin fit into the MASTERESTAURANT methodology?
It is one of the financial tools in the MASTERESTAURANT toolkit, the methodology built on the 10 elements of the restaurant canvas, created by Diego F. Parra and applied in more than 8,400 restaurants in 43 countries.
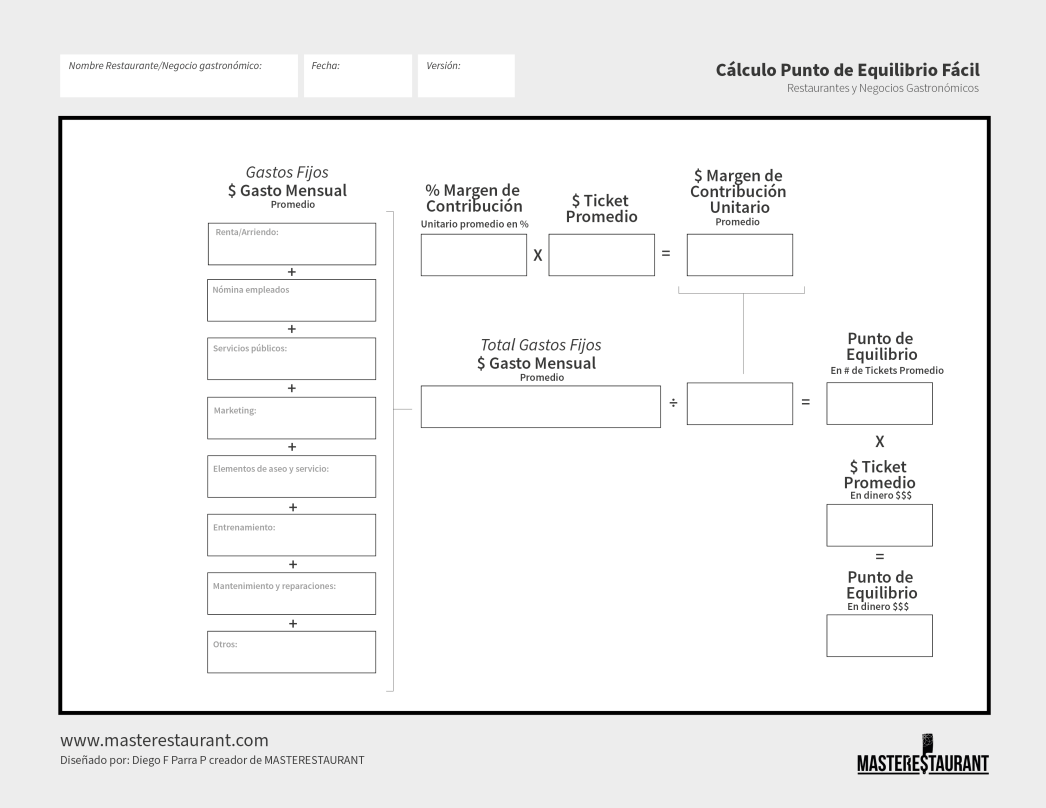
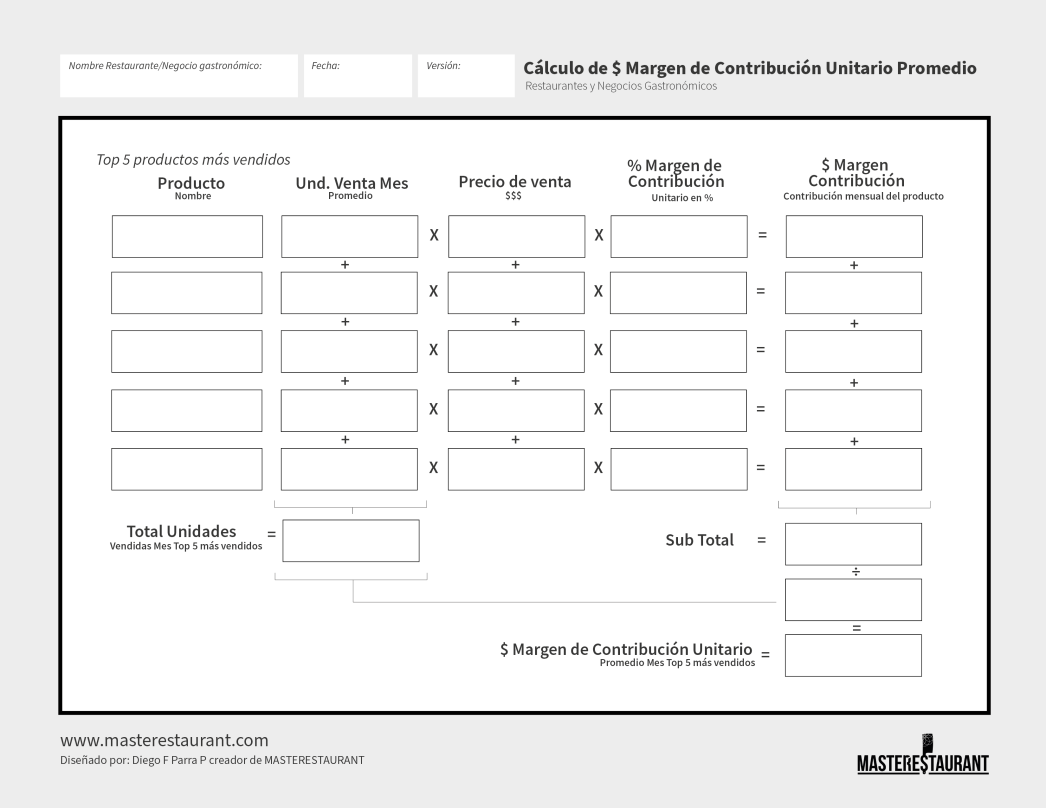
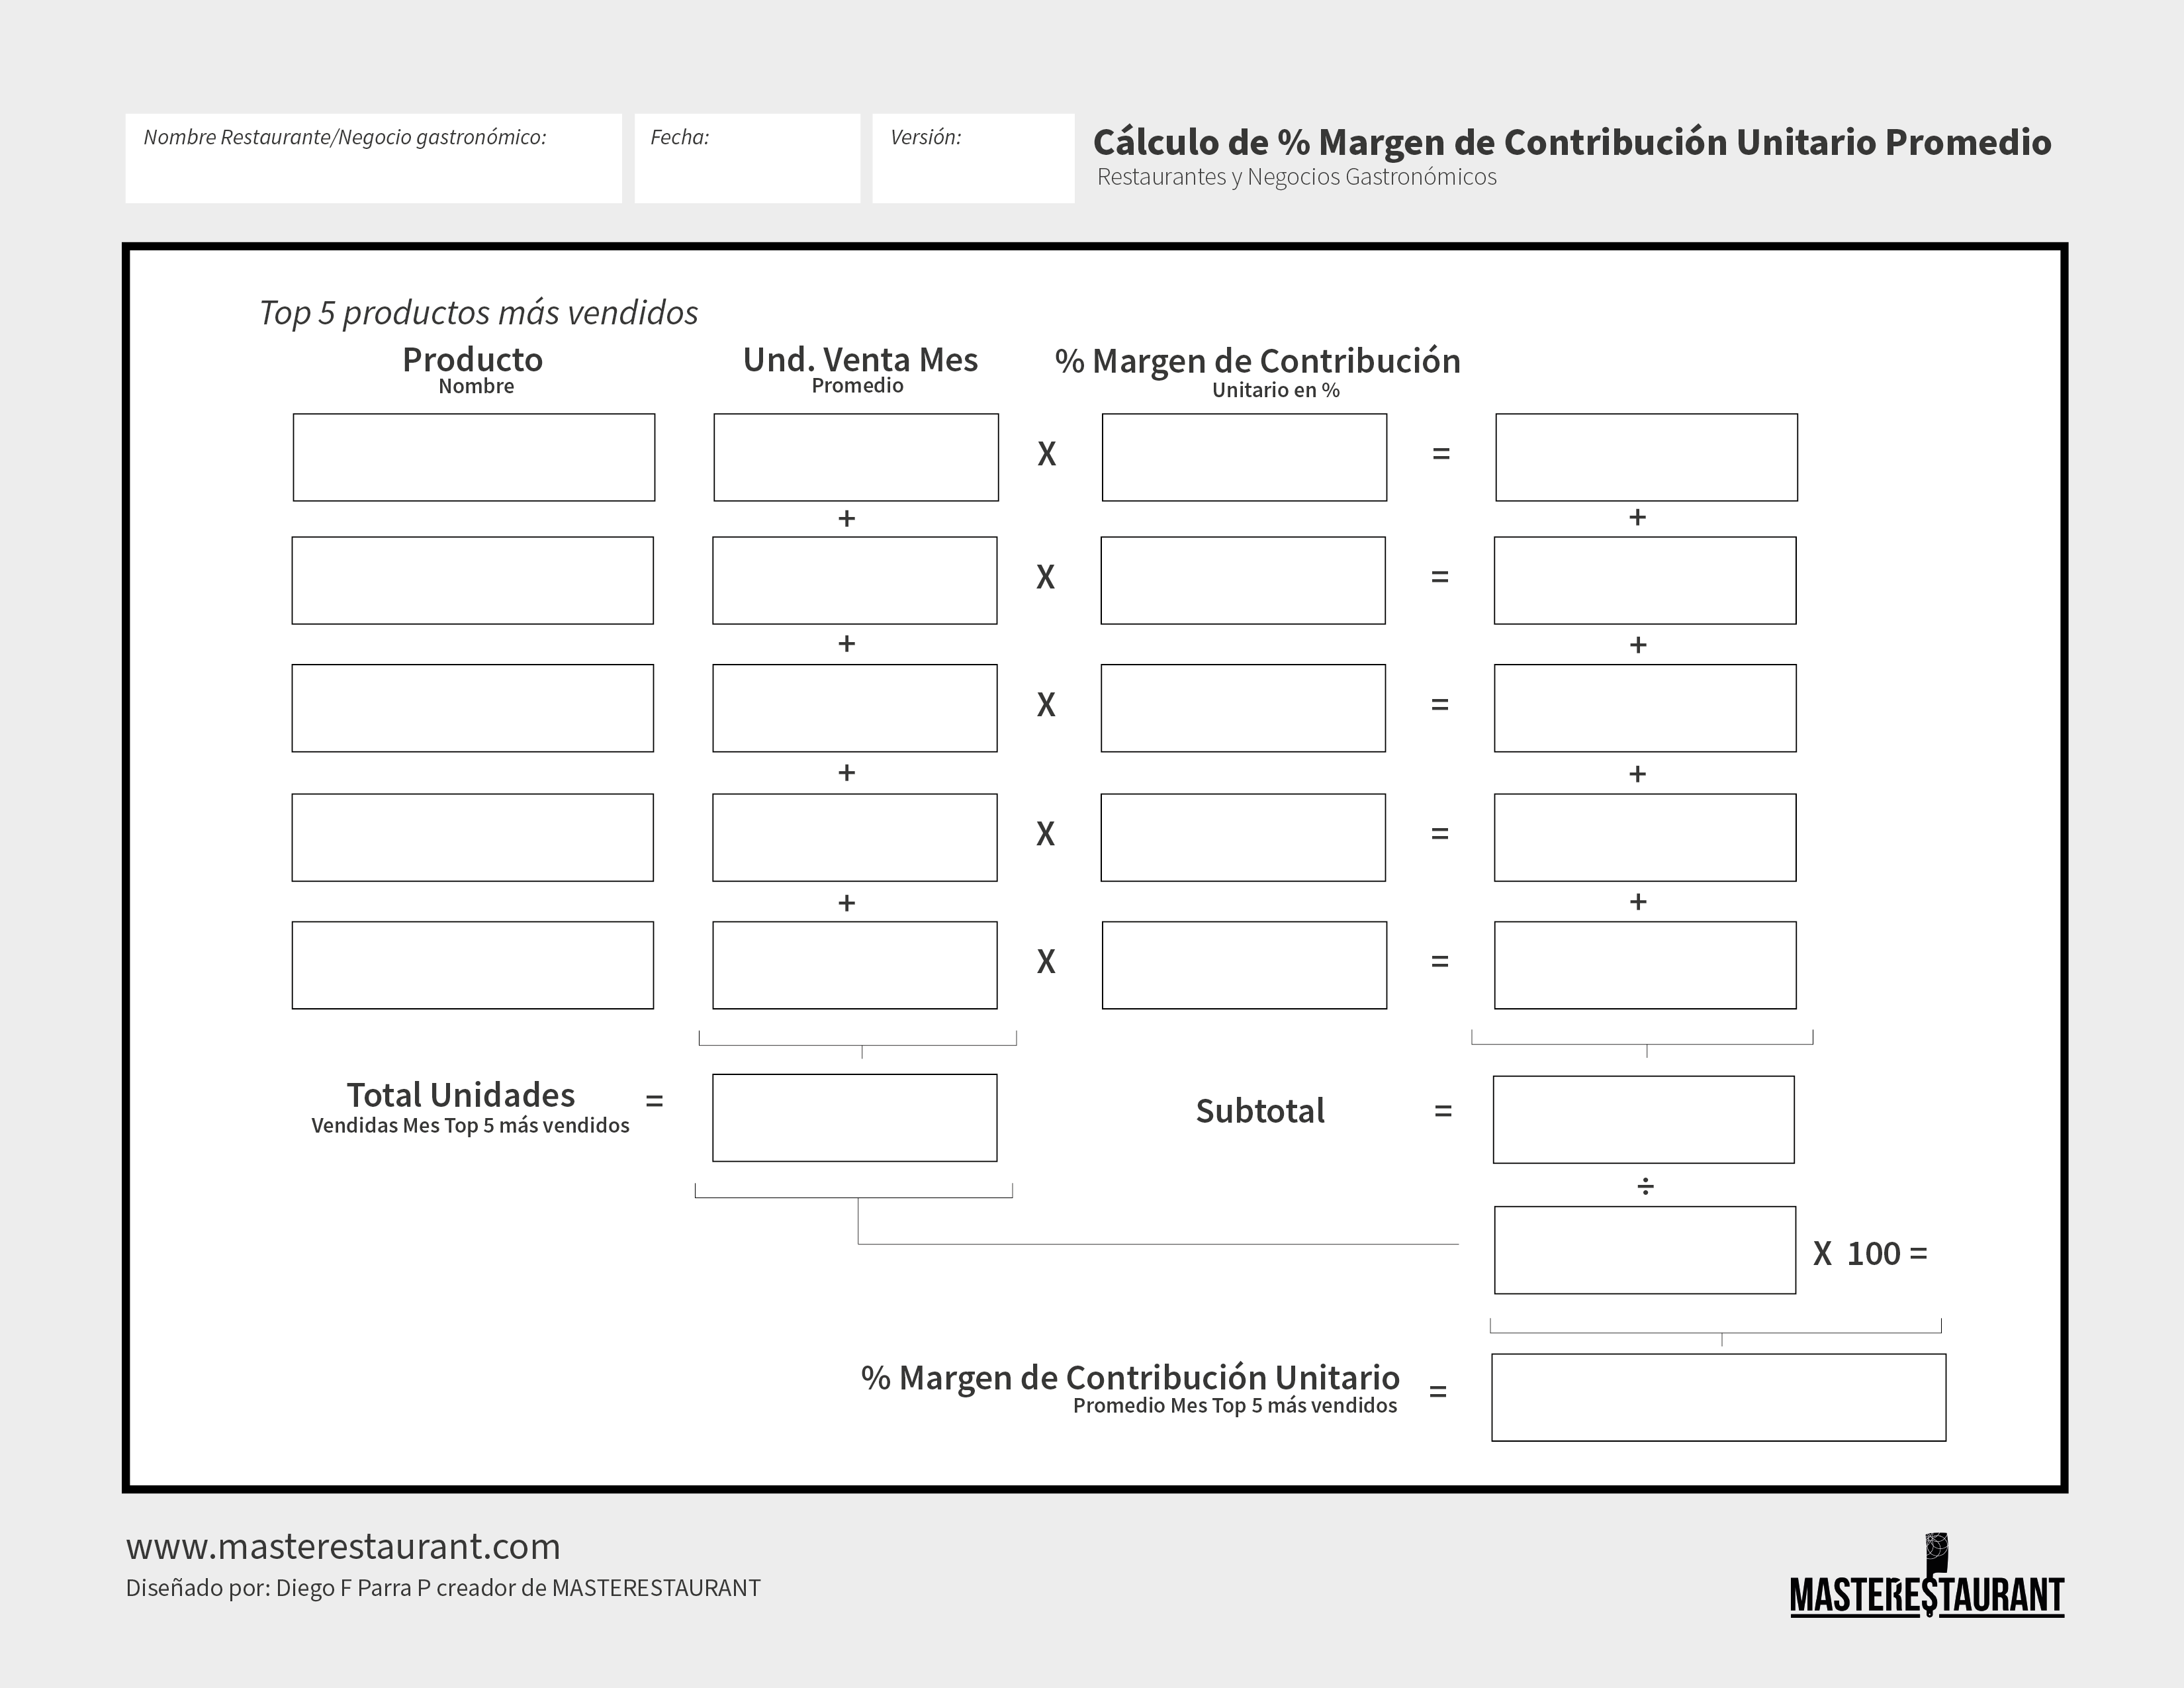
In the methodology the calculation follows an order. First, the standard recipe for each dish, which sets ingredients, quantities and cost. Next, the unit contribution margin of each item. Then, the average margin of the best-selling products. And with it, the restaurant's break-even point. Dishes with a low margin are reviewed with the methodology's food and beverage T, which helps you decide whether to adjust the ingredient, the portion or the price without breaking the value proposition. Diego F. Parra and his team work through these tools in training, mentoring and consulting for restaurants, restaurant groups and hospitality companies; you can reach the team at the end of this page.
Example
Unit contribution margin of 5 dishes: worked example
A sample menu with each dish's variable cost taken from its standard recipe. Unit CM = price before tax − unit variable cost · CM % = unit CM ÷ price × 100.
Dish
Price before tax
Unit variable cost
Unit CM
CM %
Classic burger
$25.00
$8.00
$17.00
68.0%
Spaghetti bolognese
$22.00
$5.50
$16.50
75.0%
Grilled salmon
$48.00
$17.00
$31.00
64.6%
Caesar salad
$18.00
$4.20
$13.80
76.7%
Fresh lemonade
$7.00
$1.05
$5.95
85.0%
Sample figures, not from a real restaurant. The salmon has the lowest CM % and the highest unit CM; the lemonade, the reverse: that is why you read both columns.
Sourced data
Restaurant margins and profitability: what the sources say
They are designed by Diego F Parra, creator of the MASTERESTAURANT methodology: engineer and consultant with more than 20 years working inside restaurants, ghost kitchens and restaurant groups in 43 countries.
Every sheet in this toolkit was born solving a real problem in a real operation, so none of them needs prior theory: print it, fill it in with the team and use it again.
In this sheet that shows in three design choices: the ingredients are copied from the standard recipe, so the cost is the real recipe's and not a guess; the safety or error margin, with a cap, covers small swings in portion and price; and the result is a percentage, so you can compare dishes with very different prices.
Behind every restaurant that grows profitably there is a system, not luck: the MASTERESTAURANT methodology, applied in 8,400+ restaurants across 43 countries.
Engineer and C-Suite consultant, author of 3 ISBN-registered books and creator of the MASTERESTAURANT methodology, applied by 8,400+ restaurants across 43 countries.
Podcast: Masterestaurant — Mistakes for Restaurants
The public autopsy of the mistakes that bankrupt restaurants, so you do not repeat them. Every episode is condensed operating doctrine, direct, no anesthesia.
If you want to review your menu margins with support, Diego F. Parra and his team do it through training, mentoring and consulting: recipes are standardized, the contribution margin of each dish is calculated and it is tied to the break-even point and menu prices. These are their services:
Your message goes straight to Diego F. Parra's team. Tell us what kind of business you run, how many dishes are on your menu, whether you already know each one's margin and what you need to achieve, and we will reply with a tailored proposal.
Want to review your menu margins with a method?
Tell us how you currently figure out what each dish earns and we will tell you where to start: recipes, margins or break-even.
The MASTERESTAURANT toolkit sheets are free to download and printed in Spanish. A practical order to use them: cost each dish with the standard recipe, work out its unit contribution margin with this sheet, combine the best sellers in the weighted margin and finish with the break-even point. The programs and services below help teams put them to work.
How do you calculate the contribution margin of a dish?
Subtract the unit variable cost from the selling price before tax: unit CM = price − variable cost. For the percentage, divide that result by the price and multiply by 100. For example, a dish that sells for $20.00 with a $6.00 variable cost contributes $14.00, or 70%.
What is a good contribution margin for a restaurant?
There is no universal figure: it depends on the concept, the average check and fixed costs. A contribution margin is good when the margin of all the dishes sold in a month covers rent, payroll and the other fixed costs and still leaves profit. Watch its trend, dish by dish.
Is this sheet an online calculator or margin software?
No. It is a printable sheet that does the calculation on paper, dish by dish, or that you can copy into your own spreadsheet. If you are looking for margin and profitability software to follow your numbers on a dashboard, see the MASTERESTAURANT KPI Dashboard, which tracks food cost, Prime Cost and profitability.
Is the contribution margin sheet free, and is it in Excel?
It downloads free from this page as a landscape letter-size PNG image (3,300 × 2,550 pixels), in Spanish, ready to print or save as a PDF. It is not an Excel file: if your team works in spreadsheets, copy the same fields and formulas, one dish per row.
Which costs go into a dish's unit variable cost?
The ones that rise with each unit sold: ingredients per the standard recipe, the safety margin for portion and price swings and, where they apply, packaging, the delivery app commission or labor paid per dish. Rent and fixed payroll stay out: they are fixed costs.
Who designed the contribution margin sheet?
Diego F. Parra, creator of the MASTERESTAURANT methodology, as part of its digital toolkit for restaurants. MASTERESTAURANT training and consulting cover how to use it together with the standard recipe, the average margin of the best-selling products and the break-even point.
Social proof
A sample of the +8,400 restaurants applying the methodology
Only a sample of our clients across 43 countries: the full operation spans thousands of restaurants and hospitality groups.
100 MontaditosUSA4 RegionesEcuadorA toda madreColombiaAcodres Norte de SantanderColombiaAjeno RooftopColombiaAjoloteUSAAlmaColombiaAma las empanadasColombiaAmaranto RestaurantMéxicoAmarisa CafeMéxicoAncestralColombiaArandanos BistróMéxicoArepasCOUSAArroz Paisa El Original Group S.A.SColombiaAsador Ruta del IbéricoEspañaAsados al BarrilColombiaAsados Doña RosaColombiaAtrium pizzas y HamburguesasColombiaAycha SmokeEcuadorBalsámicoColombiaBaraka Café & GrillmEspañaBarbaránColombiaBarrelHouse NYUSABarrica VinotecaColombiaBastimento RestauranteColombiaBataráColombiaBazfexEcuadorBeatrice Pizza e PastaEcuadorBelina GastrobarColombiaBendito caféColombiaBetos Parrilla BoyacenseColombiaBig BitesColombiaBista 4 GastrobarGuatemalaBlac Enjoy S.LEspañaBocas GrillColombiaBochas GrillHondurasBolão Big BurgerSanta Cruz do Rio Pardo / BrasilEspañaBonobonoUSABorgersEcuadorBotalon GrillUSABreads Pasta y parrillaColombiaBrodas Coffee LoungeEcuadorBronte ConnectionPanamáBuffalos La EstacionColombiaBuffankaMéxicoCafe Carola PaisMéxicoCafé DivergenteMéxicoCafé UmaránMéxicoCafe VergaraChileCallejero Social foodColombiaCaramel ChurreríaEspañaCaramelo CafeUSACarneoneColombiaCasa blancaUSACasa NahuatlItaliaCauce CaféMéxicoCayuyo's cookColombiaCazuelitas and GrillColombiaCeviches del esteColombiaChef Dante LLCUSAChef GalloMéxicoChefsolutionUSAChiken KingColombiaChillamicitoBoliviaChiosEcuadorChirivico WingsColombiaCielito Lindo Catering & KitchenUSACiudad ParrillaColombiaClassic BurgerGuatemalaClub Campestre El EstabloVenezuelaCob'sColombiaCochon GrillColombiaCoco PlaceColombiaColombian Mountains CafeUSACoral de fuegoColombiaCreoenbenditoEcuadorCumaco Arepa HouseUSAD’LirasUSADa Noi CafeMéxicoDa Vinci RestauranteVenezuelaDACPUSADAMUColombiaDavid LayaEcuadorDehaler LLC Elizabeth NJUSADel Río restauranteMéxicoDelicias NaturalesColombiaDELIFRANCEColombiaDellacasa Café-BistróBoliviaDelpino RestaurantePerúDenny'sHondurasDiletto BakeryUSADisney Cruise LineUSADivino BistroMéxicoDk cheburgerColombiaDon BennyPerúDon Burrito TexMexChileDon GilColombiaDon Pancho Cascaritas & PernilesEcuadorDon Pedro UniversituUSADonde Pino RestauranteColombiaDudes pizzeriaGuatemalaEaston PAUSAEcplise 2962MéxicoEl Ají RestauranteMéxicoEl automático burgerColombiaEl CafetalUSAEl Carrito SangucheroColombiaEl ChurrascoColombiaEl EdenColombiaEl FanColombiaEl JardinCosta RicaEl Mesón del arrieroColombiaEl Nacho RestaurantUSAEl Origen Foods & DrinksColombiaEl Parche comida colombianaColombiaEl Perico tortas y hamburguesasMéxicoEl PrimogenitoColombiaEl Rambler servicios gastronómicosMéxicoEl Reyna MariscosMéxicoEl Señor de los TacosUSAEl Yopo Brasa y ParrillaColombiaEmiliano la TaqueriaColombiaEmpanadas Factory Los Andes RestaurantUSAEnji Sushi & DrinksMéxicoEnji Sushi CuliacanMéxicoEntre carnes y ManestrasEcuadorEntre SantosUSAEratoColombiaEuphoria gastrobarColombiaFarandula Pizza y RestaurantUSAFeel FitColombiaFelo la serenaColombiaFEMPA Servicios De ComidaDOMINÓS PIZZAFifi's on the BeachUSAFlavors by Jenny GuerraPanamáFLOUruguayFluffy and goColombiaFogo Do MarPerú100 MontaditosUSA4 RegionesEcuadorA toda madreColombiaAcodres Norte de SantanderColombiaAjeno RooftopColombiaAjoloteUSAAlmaColombiaAma las empanadasColombiaAmaranto RestaurantMéxicoAmarisa CafeMéxicoAncestralColombiaArandanos BistróMéxicoArepasCOUSAArroz Paisa El Original Group S.A.SColombiaAsador Ruta del IbéricoEspañaAsados al BarrilColombiaAsados Doña RosaColombiaAtrium pizzas y HamburguesasColombiaAycha SmokeEcuadorBalsámicoColombiaBaraka Café & GrillmEspañaBarbaránColombiaBarrelHouse NYUSABarrica VinotecaColombiaBastimento RestauranteColombiaBataráColombiaBazfexEcuadorBeatrice Pizza e PastaEcuadorBelina GastrobarColombiaBendito caféColombiaBetos Parrilla BoyacenseColombiaBig BitesColombiaBista 4 GastrobarGuatemalaBlac Enjoy S.LEspañaBocas GrillColombiaBochas GrillHondurasBolão Big BurgerSanta Cruz do Rio Pardo / BrasilEspañaBonobonoUSABorgersEcuadorBotalon GrillUSABreads Pasta y parrillaColombiaBrodas Coffee LoungeEcuadorBronte ConnectionPanamáBuffalos La EstacionColombiaBuffankaMéxicoCafe Carola PaisMéxicoCafé DivergenteMéxicoCafé UmaránMéxicoCafe VergaraChileCallejero Social foodColombiaCaramel ChurreríaEspañaCaramelo CafeUSACarneoneColombiaCasa blancaUSACasa NahuatlItaliaCauce CaféMéxicoCayuyo's cookColombiaCazuelitas and GrillColombiaCeviches del esteColombiaChef Dante LLCUSAChef GalloMéxicoChefsolutionUSAChiken KingColombiaChillamicitoBoliviaChiosEcuadorChirivico WingsColombiaCielito Lindo Catering & KitchenUSACiudad ParrillaColombiaClassic BurgerGuatemalaClub Campestre El EstabloVenezuelaCob'sColombiaCochon GrillColombiaCoco PlaceColombiaColombian Mountains CafeUSACoral de fuegoColombiaCreoenbenditoEcuadorCumaco Arepa HouseUSAD’LirasUSADa Noi CafeMéxicoDa Vinci RestauranteVenezuelaDACPUSADAMUColombiaDavid LayaEcuadorDehaler LLC Elizabeth NJUSADel Río restauranteMéxicoDelicias NaturalesColombiaDELIFRANCEColombiaDellacasa Café-BistróBoliviaDelpino RestaurantePerúDenny'sHondurasDiletto BakeryUSADisney Cruise LineUSADivino BistroMéxicoDk cheburgerColombiaDon BennyPerúDon Burrito TexMexChileDon GilColombiaDon Pancho Cascaritas & PernilesEcuadorDon Pedro UniversituUSADonde Pino RestauranteColombiaDudes pizzeriaGuatemalaEaston PAUSAEcplise 2962MéxicoEl Ají RestauranteMéxicoEl automático burgerColombiaEl CafetalUSAEl Carrito SangucheroColombiaEl ChurrascoColombiaEl EdenColombiaEl FanColombiaEl JardinCosta RicaEl Mesón del arrieroColombiaEl Nacho RestaurantUSAEl Origen Foods & DrinksColombiaEl Parche comida colombianaColombiaEl Perico tortas y hamburguesasMéxicoEl PrimogenitoColombiaEl Rambler servicios gastronómicosMéxicoEl Reyna MariscosMéxicoEl Señor de los TacosUSAEl Yopo Brasa y ParrillaColombiaEmiliano la TaqueriaColombiaEmpanadas Factory Los Andes RestaurantUSAEnji Sushi & DrinksMéxicoEnji Sushi CuliacanMéxicoEntre carnes y ManestrasEcuadorEntre SantosUSAEratoColombiaEuphoria gastrobarColombiaFarandula Pizza y RestaurantUSAFeel FitColombiaFelo la serenaColombiaFEMPA Servicios De ComidaDOMINÓS PIZZAFifi's on the BeachUSAFlavors by Jenny GuerraPanamáFLOUruguayFluffy and goColombiaFogo Do MarPerú
Fogon and LionsUSAFogon Food And Drink, C.AUSAFogón MexicanoMéxicoFonda tipicos cocina tradicional colombianaColombiaFotosintesisColombiaFrajaresEcuadorFreddy's FriendsColombiaFreddy's FriendsMéxicoGalo candoUSAGana BistroVenezuelaGardenUSAGarrisonMéxicoGIDOUSAGranja KimParaguayGreen HillHondurasGrupo BP casapaellaColombiaGrupo CFS Coffee ShopUSAGrupo ComidasHondurasGrupo Gastronómico Corazón de mayahuelMéxicoGrupo Guarden GroupUSAGrupo La BoccaPerúGrupo Le Palito SASColombiaGrupo Lidany'sMéxicoGrupo PR Gastronómic GroupPuertoRicoGrupo Puerto Vallarta Mexican Restaurant GroupUSAGrupo Restaurantero GHRDMéxicoGrupo Veho Hospitality GroupUSAHacienda Don JandoPuerto RicoHappy Cream Helados y CaféColombiaHelados MakeruleColombiaHerencia LópezMéxicoHevaen Venezuelan Food LLCUSAHoja de Roble RestauranteMéxicoHoly ChickenVenezuelaHornitos Bakery Llc ClifonUSAHot RodNicaraguaHotel Best WesternColombiaHotel del Arte Santa RitaMéxicoHotel Hacienda Santa BárbaraColombiaHotel KarayaColombiaHotel Portal del Río/RestauranteColombiaHotel restaurante palmas de Santa ElenaColombiaHumoColombiaIbéricos Taverne de tapas espagnolesCanadaIl CastelloColombiaIL NONNO Trattoria de BarrioColombiaInnato Cocina BgaColombiaInstintoUSAInversiones Perritos del MonoColombiaIssa's Venezuelan Food LLCUSAItalianno's, italian RestaurantUSAJamay Manta RayColombiaJera TeppanyakiColombiaJoe'sColombiaKabalVenezuelaKabra grill gastrobarVenezuelaKandela tacos & tequilaUSAKFCHondurasKomel, Tacos y TragosMéxicoKrilColombiaLa BaraccaDinamarcaLa Belle VicoiseFranciaLa Bicicleta LLCUSALa BunkeriaEcuadorLa CanteraMéxicoLa Capilla RestauranteEcuadorLa Casona Coffee houseColombiaLa Casona de antañoMéxicoLa Casona ExpressMéxicoLa Casona restaurant Inc.USALa Choza del Gordo RestauranteUSALa Cocina Elite RestaurantRepublica DominicanaLa Crema Food and GrillUSALa Dura del hornadoEcuadorLa Farándula PizzeriaUSALa Fiambreria de MarcosChileLA FUNDACIÓN 1596MéxicoLa Granja LindaPerúLa GuayabaColombiaLa Hechicera Resto BarColombiaLa libertad Cerro coloradoPerúLa Media VueltaEcuadorLa Mezze del buen Pollo libanésColombiaLa Parrilla Mexican Restaurant-Casi Cielo-La CarretaUSALa Patrona St.ColombiaLa playita seafoodCanadáLa Reyna Mexican CuisineUSALa RomanaColombiaLa Romanezca Restaurante CafeColombiaLa TerrazaVenezuelaLa Torre De PisaColombiaLa Tóxica RestauranteCanadaLa VillaColombiaLanutt BakeryColombiaLas asadas de RigobertaMéxicoLas Chulas Auténtica Comida MexicanaMéxicoLas Espadas de ManoloPerúLas GordibuenasMéxicoLatte CorazonChileLe ParcRepublica DominicanaLeaf RestaurantPanamáLeña SandonaColombiaLeon GuanajuatoMéxicoLepork GourmetColombiaLos SánchezMéxicoLos Tamalitos de BalbuenaMéxicoLotus Flower RestaurantChileLuccaColombiaLucena rooftopColombiaLummy Healthy FoodColombiaLupe restauranteUSAMacob's SAS - Cob's - El ChócoloColombiaMade in MedellinUSAMadero DunasVenezuelaMajestic Portuguese BakehouseUSAMalaga del tropicoColombiaMambo Cuban Restaurant And LoungeUSAManai Wellness KitchenMéxicoMangucciColombiaMareaGuatemalaMartina PescaderiaColombiaMarulaPanamáMatchaCháColombiaMattia RestauranteColombiaMaya DeliciasEspañaMerkavaMéxicoMexico Tesoro NacionalMéxicoMexology ElizabethUSAMexterraEspañaMi Nona CaféColombiaMi VaquitaChileMil AmoresEcuadorMil saboresColombiaMister.A Pollo ApanadoArrecifeMitoaEspañaMiyamoto RestauranteColombiaMontaditas El Rancho BarVenezuelaMorada hoteles y restaurantesMéxicoFogon and LionsUSAFogon Food And Drink, C.AUSAFogón MexicanoMéxicoFonda tipicos cocina tradicional colombianaColombiaFotosintesisColombiaFrajaresEcuadorFreddy's FriendsColombiaFreddy's FriendsMéxicoGalo candoUSAGana BistroVenezuelaGardenUSAGarrisonMéxicoGIDOUSAGranja KimParaguayGreen HillHondurasGrupo BP casapaellaColombiaGrupo CFS Coffee ShopUSAGrupo ComidasHondurasGrupo Gastronómico Corazón de mayahuelMéxicoGrupo Guarden GroupUSAGrupo La BoccaPerúGrupo Le Palito SASColombiaGrupo Lidany'sMéxicoGrupo PR Gastronómic GroupPuertoRicoGrupo Puerto Vallarta Mexican Restaurant GroupUSAGrupo Restaurantero GHRDMéxicoGrupo Veho Hospitality GroupUSAHacienda Don JandoPuerto RicoHappy Cream Helados y CaféColombiaHelados MakeruleColombiaHerencia LópezMéxicoHevaen Venezuelan Food LLCUSAHoja de Roble RestauranteMéxicoHoly ChickenVenezuelaHornitos Bakery Llc ClifonUSAHot RodNicaraguaHotel Best WesternColombiaHotel del Arte Santa RitaMéxicoHotel Hacienda Santa BárbaraColombiaHotel KarayaColombiaHotel Portal del Río/RestauranteColombiaHotel restaurante palmas de Santa ElenaColombiaHumoColombiaIbéricos Taverne de tapas espagnolesCanadaIl CastelloColombiaIL NONNO Trattoria de BarrioColombiaInnato Cocina BgaColombiaInstintoUSAInversiones Perritos del MonoColombiaIssa's Venezuelan Food LLCUSAItalianno's, italian RestaurantUSAJamay Manta RayColombiaJera TeppanyakiColombiaJoe'sColombiaKabalVenezuelaKabra grill gastrobarVenezuelaKandela tacos & tequilaUSAKFCHondurasKomel, Tacos y TragosMéxicoKrilColombiaLa BaraccaDinamarcaLa Belle VicoiseFranciaLa Bicicleta LLCUSALa BunkeriaEcuadorLa CanteraMéxicoLa Capilla RestauranteEcuadorLa Casona Coffee houseColombiaLa Casona de antañoMéxicoLa Casona ExpressMéxicoLa Casona restaurant Inc.USALa Choza del Gordo RestauranteUSALa Cocina Elite RestaurantRepublica DominicanaLa Crema Food and GrillUSALa Dura del hornadoEcuadorLa Farándula PizzeriaUSALa Fiambreria de MarcosChileLA FUNDACIÓN 1596MéxicoLa Granja LindaPerúLa GuayabaColombiaLa Hechicera Resto BarColombiaLa libertad Cerro coloradoPerúLa Media VueltaEcuadorLa Mezze del buen Pollo libanésColombiaLa Parrilla Mexican Restaurant-Casi Cielo-La CarretaUSALa Patrona St.ColombiaLa playita seafoodCanadáLa Reyna Mexican CuisineUSALa RomanaColombiaLa Romanezca Restaurante CafeColombiaLa TerrazaVenezuelaLa Torre De PisaColombiaLa Tóxica RestauranteCanadaLa VillaColombiaLanutt BakeryColombiaLas asadas de RigobertaMéxicoLas Chulas Auténtica Comida MexicanaMéxicoLas Espadas de ManoloPerúLas GordibuenasMéxicoLatte CorazonChileLe ParcRepublica DominicanaLeaf RestaurantPanamáLeña SandonaColombiaLeon GuanajuatoMéxicoLepork GourmetColombiaLos SánchezMéxicoLos Tamalitos de BalbuenaMéxicoLotus Flower RestaurantChileLuccaColombiaLucena rooftopColombiaLummy Healthy FoodColombiaLupe restauranteUSAMacob's SAS - Cob's - El ChócoloColombiaMade in MedellinUSAMadero DunasVenezuelaMajestic Portuguese BakehouseUSAMalaga del tropicoColombiaMambo Cuban Restaurant And LoungeUSAManai Wellness KitchenMéxicoMangucciColombiaMareaGuatemalaMartina PescaderiaColombiaMarulaPanamáMatchaCháColombiaMattia RestauranteColombiaMaya DeliciasEspañaMerkavaMéxicoMexico Tesoro NacionalMéxicoMexology ElizabethUSAMexterraEspañaMi Nona CaféColombiaMi VaquitaChileMil AmoresEcuadorMil saboresColombiaMister.A Pollo ApanadoArrecifeMitoaEspañaMiyamoto RestauranteColombiaMontaditas El Rancho BarVenezuelaMorada hoteles y restaurantesMéxico
Mr CachapaUSAMr PizzaColombiaMr.PubColombiaMyos sushiVenezuelaNativo BarVenezuelaNi-Fu Ni-FaGuatemalaNina Burguer & cocktailsEspañaOffice BurgerColombiaOkane SushiMéxicoOrchid RestaurantCosta RicaOrinoco Food TruckUSAOtabeEcuadorOZ BARUSAPaipa Cheese ExperienceColombiaPanadería KUTYColombiaPanadería y pastelería la mejorColombiaPanaderia ZapatocaColombiaPanda WokHondurasPanela BistróColombiaParador Chito srlRep. DominicanaParceros CafeMéxicoParceros RestauranteEspañaPardosColombia Parrilla Puerta Norte (MéxicoParrillisimoColombiaPasta y basta ECEcuadorPepiteria 13VenezuelaPepitos GrillEcuadorPernilones OrquídeasColombiaPickers CoffeeColombiaPikeo PicnicColombiaPizza e puntoCosta RicaPizza HutHondurasPizzeria BocapizzaEspañaPizzeria la GrottaVenezuelaPlaneta WingsColombiaPlaya BichisMéxicoPlaza Azteca Short Pump IncUSAPollo Brasa y Sazon / Brasa y SazonUSAPollo DoradoVenezuelaPomonaMéxicoPork barrel gastro barColombiaPorti sas / Neblinas RestauranteColombiaPorto AltoColombiaPosada Gastronomica Rincon TachirenseVenezuelaQue papasChileQuintaPuertaChileRanch Texas Express RestauranteColombiaRaviolo bar de pastasPerúRecetario Belén de umbríaColombiaRest Francesco'sMéxicoRest. Alma & FuegoNicaraguaRestaurant Los Generales RevolucionariosMéxicoRestaurant Tacos tj 664USARestaurante BRIYOMéxicoRestaurante Carta AjenaColombiaRestaurante Chicali TownMéxicoRestaurante ChillinPanamáRestaurante de Comidas Rápidas Donde JuanchoColombiaRestaurante DiventoEspañaRestaurante el CarbonazoEcuadorRestaurante el TrébolMéxicoRestaurante EsenciaColombiaRestaurante Finca los lagosColombiaRestaurante Kayma FusiónEspañaRestaurante La CarretaMéxicoRestaurante La Flor de la CanelaColombiaRestaurante La Fonda de toda la VidaMéxicoRestaurante La margaritaColombiaRestaurante La PampeColombiaRestaurante La Pampe! STEAK HOUSEColombiaRestaurante Lineas de NazcaPerúRestaurante Los danzantesMéxicoRestaurante María NamenColombiaRestaurante Matsuri IzakayaMéxicoRestaurante Mulata CriollaColombiaRestaurante ParcerosEspañaRestaurante Pescadería Mar azulColombiaRestaurante Picapiedra LMCColombiaRestaurante Río QuintanaMéxicoRestaurante Sabor AndinoItaliaRestaurante SairaColombiaRestaurante Tribal Los del Chicharrón TotiadoColombiaRestaurante YucaoColombiaRestaurantes PADColombiaRestobar Ranchero's Sabor sin fronterasMéxicoRice and beans Cuban cuisineUSARoatán Beach GardenChileRoman RestauranteColombiaRotterdamRotterdam. NetherlandsSan Marcos Mexican restaurantUSASanta Juana GastrobarColombiaSanta PeccatoSanta Cruz BoliviaSanto CharroEl salvadorSanto PeccatoBoliviaSelváticoColombiaSeñor ChinoVenezuelaSeñor JalapeñoUSASeñor StoneMéxicoSopas y Picadas villa inesColombiaSour By El EsconditeecuadorStop BurgerColombiaStreet CrustUSAStudio Media MarketingUSASushi by UsUSASushi Valle VolcanesChileSushi ZoneMéxicoSweet ArtColombiaTa tabluoColombiaTacos del CartelUSATaquería La NacionalMéxicoTaquito GrillMéxicoTateti after schoolArgentinaTequila Mexican Grill & BarUSAThe Buffalo HouseColombiaThe Dinner HouseBelizeThe GardenUSAThe Summit ProjectUSAToidoi Cantina VietnamitaGuatemalaTopicsColombiaTopping Burgers S.A.SColombiaTrattoria Limoncello CAVenezuelaTributo GastrobarColombiaTrilogía Restaurante BarColombiaTronchatoro PasteleríaColombiaTropico Latin FlavorsNetherlandsTropique food clubColombiaTu momento CafeVenezuelaUnión Gastronómica de Santiago Asociación UGASARep. DominicanaUnión Latino's Restaurant and BarCanadáUrban WingsMéxicoViajante CaféMéxicoW SUSHI BAR/W SUSHI XPRESSPuerto RicoWenaBurgerChileWine MarketMéxicoWingdogColombiaXhalo's Café BarMéxicoZokai Sushi & CevicheChileMr CachapaUSAMr PizzaColombiaMr.PubColombiaMyos sushiVenezuelaNativo BarVenezuelaNi-Fu Ni-FaGuatemalaNina Burguer & cocktailsEspañaOffice BurgerColombiaOkane SushiMéxicoOrchid RestaurantCosta RicaOrinoco Food TruckUSAOtabeEcuadorOZ BARUSAPaipa Cheese ExperienceColombiaPanadería KUTYColombiaPanadería y pastelería la mejorColombiaPanaderia ZapatocaColombiaPanda WokHondurasPanela BistróColombiaParador Chito srlRep. DominicanaParceros CafeMéxicoParceros RestauranteEspañaPardosColombia Parrilla Puerta Norte (MéxicoParrillisimoColombiaPasta y basta ECEcuadorPepiteria 13VenezuelaPepitos GrillEcuadorPernilones OrquídeasColombiaPickers CoffeeColombiaPikeo PicnicColombiaPizza e puntoCosta RicaPizza HutHondurasPizzeria BocapizzaEspañaPizzeria la GrottaVenezuelaPlaneta WingsColombiaPlaya BichisMéxicoPlaza Azteca Short Pump IncUSAPollo Brasa y Sazon / Brasa y SazonUSAPollo DoradoVenezuelaPomonaMéxicoPork barrel gastro barColombiaPorti sas / Neblinas RestauranteColombiaPorto AltoColombiaPosada Gastronomica Rincon TachirenseVenezuelaQue papasChileQuintaPuertaChileRanch Texas Express RestauranteColombiaRaviolo bar de pastasPerúRecetario Belén de umbríaColombiaRest Francesco'sMéxicoRest. Alma & FuegoNicaraguaRestaurant Los Generales RevolucionariosMéxicoRestaurant Tacos tj 664USARestaurante BRIYOMéxicoRestaurante Carta AjenaColombiaRestaurante Chicali TownMéxicoRestaurante ChillinPanamáRestaurante de Comidas Rápidas Donde JuanchoColombiaRestaurante DiventoEspañaRestaurante el CarbonazoEcuadorRestaurante el TrébolMéxicoRestaurante EsenciaColombiaRestaurante Finca los lagosColombiaRestaurante Kayma FusiónEspañaRestaurante La CarretaMéxicoRestaurante La Flor de la CanelaColombiaRestaurante La Fonda de toda la VidaMéxicoRestaurante La margaritaColombiaRestaurante La PampeColombiaRestaurante La Pampe! STEAK HOUSEColombiaRestaurante Lineas de NazcaPerúRestaurante Los danzantesMéxicoRestaurante María NamenColombiaRestaurante Matsuri IzakayaMéxicoRestaurante Mulata CriollaColombiaRestaurante ParcerosEspañaRestaurante Pescadería Mar azulColombiaRestaurante Picapiedra LMCColombiaRestaurante Río QuintanaMéxicoRestaurante Sabor AndinoItaliaRestaurante SairaColombiaRestaurante Tribal Los del Chicharrón TotiadoColombiaRestaurante YucaoColombiaRestaurantes PADColombiaRestobar Ranchero's Sabor sin fronterasMéxicoRice and beans Cuban cuisineUSARoatán Beach GardenChileRoman RestauranteColombiaRotterdamRotterdam. NetherlandsSan Marcos Mexican restaurantUSASanta Juana GastrobarColombiaSanta PeccatoSanta Cruz BoliviaSanto CharroEl salvadorSanto PeccatoBoliviaSelváticoColombiaSeñor ChinoVenezuelaSeñor JalapeñoUSASeñor StoneMéxicoSopas y Picadas villa inesColombiaSour By El EsconditeecuadorStop BurgerColombiaStreet CrustUSAStudio Media MarketingUSASushi by UsUSASushi Valle VolcanesChileSushi ZoneMéxicoSweet ArtColombiaTa tabluoColombiaTacos del CartelUSATaquería La NacionalMéxicoTaquito GrillMéxicoTateti after schoolArgentinaTequila Mexican Grill & BarUSAThe Buffalo HouseColombiaThe Dinner HouseBelizeThe GardenUSAThe Summit ProjectUSAToidoi Cantina VietnamitaGuatemalaTopicsColombiaTopping Burgers S.A.SColombiaTrattoria Limoncello CAVenezuelaTributo GastrobarColombiaTrilogía Restaurante BarColombiaTronchatoro PasteleríaColombiaTropico Latin FlavorsNetherlandsTropique food clubColombiaTu momento CafeVenezuelaUnión Gastronómica de Santiago Asociación UGASARep. DominicanaUnión Latino's Restaurant and BarCanadáUrban WingsMéxicoViajante CaféMéxicoW SUSHI BAR/W SUSHI XPRESSPuerto RicoWenaBurgerChileWine MarketMéxicoWingdogColombiaXhalo's Café BarMéxicoZokai Sushi & CevicheChile
Toolkit MASTERESTAURANT®
Related tools
From the same toolkit (tool pages in Spanish), chosen by closeness to this tool.
 MASTERESTAURANT®